

USAA Mobile
4.7

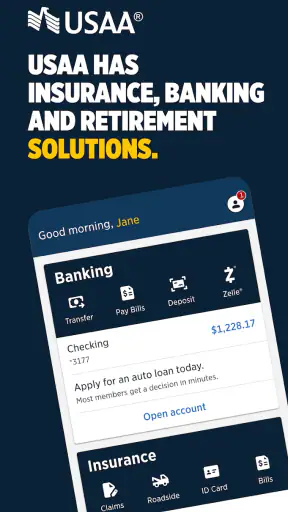
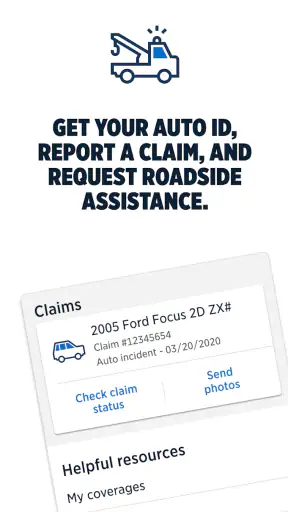
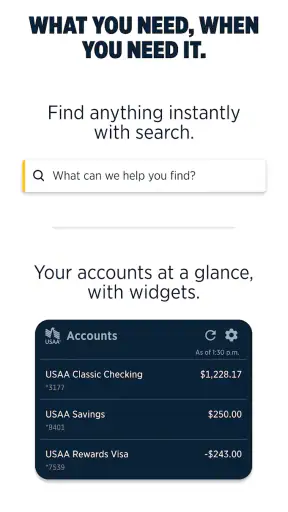
Managing money from a phone is most useful when it removes a chain of small tasks rather than simply displaying an account balance. I looked at USAA Mobile with that practical standard in mind: starting with an everyday financial need, moving through the app, and seeing how smoothly the result reaches the next person or account. It is a free finance app from USAA that brings insurance, banking, and investment accounts into one mobile experience, so its main appeal is less about one clever tool and more about keeping related parts of a financial life together.
That combination makes it especially relevant for someone who already uses USAA for more than one service. Instead of switching between a banking app, an insurance portal, and a separate investment dashboard, I can approach those responsibilities from the same place. The trade-off is just as important: people who do not use USAA services will find much less reason to install it, and anyone looking for a general-purpose money app may prefer a provider that is not tied to one institution.
From a real-life money problem to a finished task
Imagine I am leaving for work and realize that an insurance payment needs attention, while I also want to check whether a recent bank transaction has cleared. In a typical setup, I might open one app for checking, another website for insurance, and perhaps a third service for investments. With USAA Mobile, the starting condition is more unified. I sign in, choose the area that matches the task, and work from the same USAA relationship instead of rebuilding my context each time.
The first useful habit is to decide what outcome I need before opening the app. If I am checking available money, I should go to banking. If I am reviewing coverage or handling an insurance-related task, I should stay in the insurance area. If I am monitoring longer-term holdings, the investment section is the relevant destination. That sounds obvious, but separating the goal from the product name prevents the common mistake of wandering through a financial app without knowing whether I am checking, paying, transferring, or reviewing.
In my experience, the value of this arrangement appears when several tasks are connected. A vehicle expense can affect my bank balance and my insurance planning. A deposit may be relevant before I make a payment. An investment account may matter when I am reviewing the bigger picture rather than today’s spending. The app does not need to make every decision for me; it simply gives me a shared starting point for those related accounts.
The app is aimed at a broad audience, with an Everyone content rating, but that does not mean every financial workflow feels equally simple. A first-time user still needs to understand which USAA service owns a particular task and what kind of account is being viewed. The interface can bring services together, but it cannot remove the need to read payment details, account names, and confirmation screens carefully.
Step one: entering with a clear purpose
Once I open the app, I treat the first screen as a launch point rather than a place to linger. I look for the account or service connected to my immediate goal, then verify that I am acting in the right area. This matters more in a combined financial app than in a single-purpose banking tool because banking, insurance, and investing have different consequences and different kinds of information.
A practical workflow is to review the relevant balance or account status first, then decide whether an action is actually necessary. For example, if I am preparing to make a payment, I want to know which funding account I am using and whether the amount fits my available money. If I am checking insurance, I want to confirm that I am viewing the correct policy before moving further. This two-step pause is small, but it reduces the chance of completing a valid action in the wrong place.
One of the less obvious strengths is that the app encourages a “check, then act” routine across services. A standalone payment app may push me directly toward sending money, while a combined account view makes it easier to see the surrounding context first. I would not rely on that convenience blindly, but it is helpful when my decision depends on more than one USAA relationship.
There is also a useful distinction between convenience and speed. Having everything under one sign-in can make the overall process shorter, but a financial task should not be rushed just because the navigation feels familiar. I still read the destination, amount, and account details before confirming. That is particularly important when moving from a review screen to an irreversible action.
Step two: moving from review to action
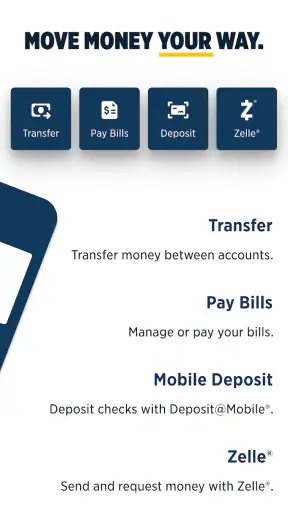
After locating the right service, I follow the task in a deliberate order: identify the account, inspect the details, make the change or request, and look for the final confirmation. This is where a mobile finance app earns its place. I can handle a small administrative job while away from a desktop instead of postponing it until I remember later.
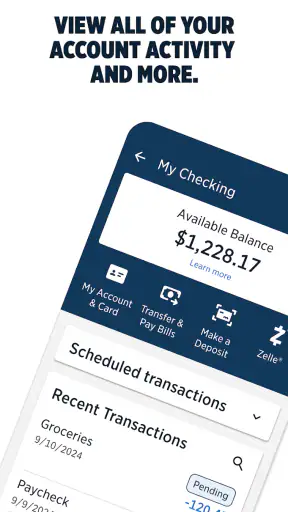
For banking, the workflow is most useful when I need a quick view of account activity or want to manage a routine money task. For insurance, the benefit is having coverage-related information close to the same financial tools I use for payments. For investments, the app provides a convenient way to keep those accounts in the same overall picture. I see this as a coordination advantage, not a substitute for careful financial planning.
A concrete scenario is a weekend trip. Before leaving, I can review the bank account I expect to use, check the insurance information relevant to the trip or vehicle, and glance at investments without opening separate services. If a payment or account review is needed, I can complete it from the same mobile environment. The outcome is not dramatic, but it is practical: fewer context switches and a clearer sense of which USAA service handles each part of the preparation.
Another useful workflow is end-of-month housekeeping. I might review recent banking activity, confirm that an insurance-related payment is accounted for, and then look at investment balances as a separate long-term check. Doing these in sequence helps me avoid confusing a short-term cash question with a long-term investment question. The app’s unified access supports that separation while keeping the tasks nearby.
My best tip is to treat the confirmation screen as part of the task, not as an afterthought. A completed-looking navigation step is not the same as a finished financial action. I check that the app has accepted the request and retain whatever in-app status or record is shown before closing it. This habit is more valuable than trying to move through the menus as quickly as possible.
The handoffs between banking, insurance, and investing
The most interesting part of USAA Mobile is not any single section; it is the handoff between sections. I may begin with a bank balance, move to insurance to review a related obligation, and then switch to investments for a broader financial snapshot. Those handoffs are where a unified app can feel substantially better than a collection of unrelated alternatives.
Still, the handoff does not mean the products become one account. I remain responsible for recognizing which service I am using and what the information means. A bank balance answers a different question from an investment value, and an insurance view is not a spending ledger. The app brings them into one access point, but I should keep those mental boundaries intact.
This is also where the app may be less comfortable for people who prefer highly specialized tools. A dedicated investing platform can feel more focused to someone who spends most of the day analyzing investments. A budgeting app may be better for a household that wants detailed category rules and a broad view across several financial institutions. USAA Mobile is strongest when the priority is convenient access to USAA services, not when the user wants one neutral command center for every provider.
The developer, USAA, gives the app a clear ecosystem advantage for its own customers. If I already have banking, insurance, and investment relationships there, the handoff is meaningful because the services belong to the same financial provider. If my accounts are spread across unrelated institutions, that advantage becomes much smaller. In that situation, a multi-provider aggregator or a dedicated budgeting tool may reduce more work than this app can.
One trade-off I noticed in this model is attention. A combined app can make it tempting to browse areas that are not part of the immediate task. That may be useful during a planned financial review, but it can also lead to unnecessary checking. I prefer to enter with one question, answer it, and then decide whether another section deserves a separate review.
What the finished result looks like
The result of a successful session is usually modest but valuable: I know where my money stands, I have handled the relevant USAA task, and I can leave without opening another service to finish the same chain. That is the app’s strongest everyday promise. It reduces administrative friction for customers whose financial life is already centered on USAA.
The app’s public reception supports that impression. It has a 4.7 average from around 497 thousand ratings, with more than 10 million installs. Those figures do not guarantee that every screen will suit every user, but they show that the mobile experience has reached a large audience and is widely regarded positively.
I also appreciate that the app is free to install. The absence of an app price makes it easy for an existing USAA customer to try the mobile workflow without adding a separate purchase decision. That does not change the terms or costs of any financial product accessed through it, so I would still distinguish the app’s free download from the financial services themselves.
The current version is 11.15.2 and requires at least operating system version 12. Before installing, I would check that the phone meets that requirement, especially if it is an older device. Once installed, I would also keep the operating system and app current when updates are available, since a finance app is not a good place to ignore basic maintenance.
For a household, the practical outcome can be fewer “which website handles this?” moments. One person can check banking while another needs insurance information, and both are working within the same general mobile environment. That does not solve every shared-finance issue, but it makes the starting point easier to remember than a scattered collection of provider portals.
Where the workflow breaks down
The first clear limitation is membership relevance. USAA Mobile is not a general finance app that becomes useful simply because it is well rated. Its value depends on having USAA accounts or services to manage. Someone who banks elsewhere, carries insurance elsewhere, and invests through another provider should skip it rather than install it hoping for a universal dashboard.
The second limitation is specialization. If my main goal is detailed budgeting across many institutions, I would look elsewhere. If I want deep investment research, portfolio analysis, or a tool built primarily around trading decisions, a dedicated investment service may be a better fit. The combined design is convenient, but convenience can come at the cost of depth in any one financial discipline.
A third point is the risk of treating visibility as understanding. Seeing banking, insurance, and investments together can create a reassuring overview, but a quick glance is not a complete financial review. I still need to interpret cash flow, coverage, and investment risk separately. The app helps me reach the information; it does not replace judgment.
There can also be friction when a task crosses service boundaries. I may know the outcome I want, yet still need to understand which USAA area owns the next step. When that happens, I slow down and return to the account or product label rather than guessing. That approach is less frustrating than repeatedly backing out of screens after choosing the wrong service.
Finally, mobile convenience is not ideal for every situation. A small screen is fine for a quick check or routine action, but a complicated financial review may be easier with more space and a longer uninterrupted session. I would use the app for access and administration, then move to a larger-screen workflow when I need to compare many details carefully.
Who should use it, and who should choose something else?
I would recommend USAA Mobile to an existing USAA customer who wants banking, insurance, and investment access in one place. It is particularly suitable for people who handle routine financial administration from a phone and value a consistent starting point more than extensive customization. Families and busy users may appreciate the reduced switching between separate service portals.
I would be more cautious recommending it to someone who only wants a budgeting tool, a neutral account aggregator, or a specialist investment workspace. In those cases, the app’s connection to USAA is not an advantage. A service designed around multiple outside institutions or a single financial specialty may offer a clearer workflow.
My final test is simple: can the app take me from a real question to a confirmed result without making me lose track of which service I am using? For USAA customers, the answer is often yes. The strongest experience comes from planning the task, checking the correct account, respecting the handoffs, and verifying the outcome before leaving.
Overall, I see USAA Mobile as a practical access point rather than a complete replacement for every financial tool. Its free mobile format, broad USAA coverage, and strong user reception make it an easy recommendation for people already inside that ecosystem. I would install it for convenient day-to-day management, while keeping realistic expectations about specialized budgeting, investing depth, and the need to review important actions carefully.
4.7
66.11K Reviews
Pros
- Quick access to account balances
- transactions
- and payment details.
- Secure login options include biometric authentication on supported devices.
- Easy mobile check deposit with clear photo-capture guidance.
- Useful tools for locating ATMs
- branches
- and nearby service options.
- Policy and insurance information is conveniently available in one app.
Cons
- Some features may be limited to eligible USAA members and account types.
- The app can feel crowded when switching between banking and insurance services.
- Deposit availability and limits may vary depending on account history.
- Occasional updates may change menu locations or the overall navigation flow.
- Certain complex requests still require contacting customer support directly.


